
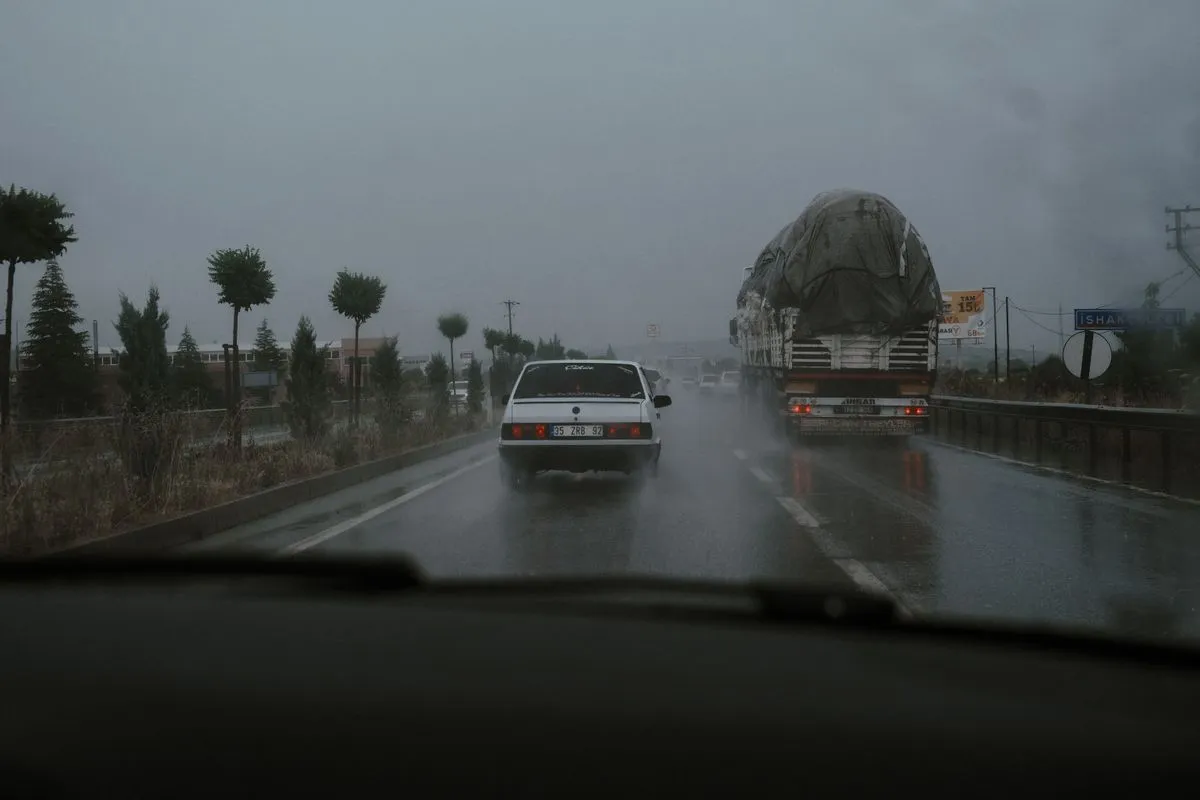
Natural-rubber futures pushed higher in October as heavy rain, flooding and uneven El Niño effects disrupted collection in Southeast Asia, but the evidence still points to a supply-risk premium rather than a confirmed regional shortage. Southern Thailand faced rainfall and flash-flood warnings that threatened tapping through October 28, while improving conditions in northern Thailand allowed farmers to resume work. Indonesia remained the weaker link, with raw-material shortages reported alongside weather-related production concerns.
The distinction matters for buyers. A force majeure, a shipment delay and a declared allocation are different events, and none is established here for a named natural-rubber producer or route. What the October notices support is a risk to near-term feedstock availability, not a verified allocation schedule for tire or rubber-goods processors.
Southern Thailand collection
Rubber futures rose to about 257 US cents per kilogram on October 26, close to the highest level since 2013. Heavy rain and flash-flood warnings across southern Thailand were identified as a threat to tapping activity through October 28. That is a direct operational risk: fields cannot be tapped normally when access, collection or working conditions fail. It is not yet a measured loss of monthly output.
The geographic split is just as important. Rainfall improved in northern Thailand, where farmers gradually resumed tapping. Southern Thailand therefore cannot be used as a proxy for the whole country, and a recovery in northern collection does not clear the southern disruption. Fourth-quarter production is normally a key seasonal supply window, so the market is watching whether lost tapping days are recovered as the peak season progresses.
No restart window is on the notice beyond the October 28 weather risk. Buyers should therefore separate material already in a confirmed warehouse or shipment from expectations that Thai field supply will normalize.
Indonesia's raw-material gap
Indonesia supplies a second warning signal. The Japan Exchange Group's October 26 weekly report said raw materials remained scarce in some producing countries, including Indonesia, while El Niño-related conditions continued to affect cup-lump quality and tapping activity. The statement identifies a feedstock problem, but it does not name a plant, producer, grade, port, vessel or customer allocation.
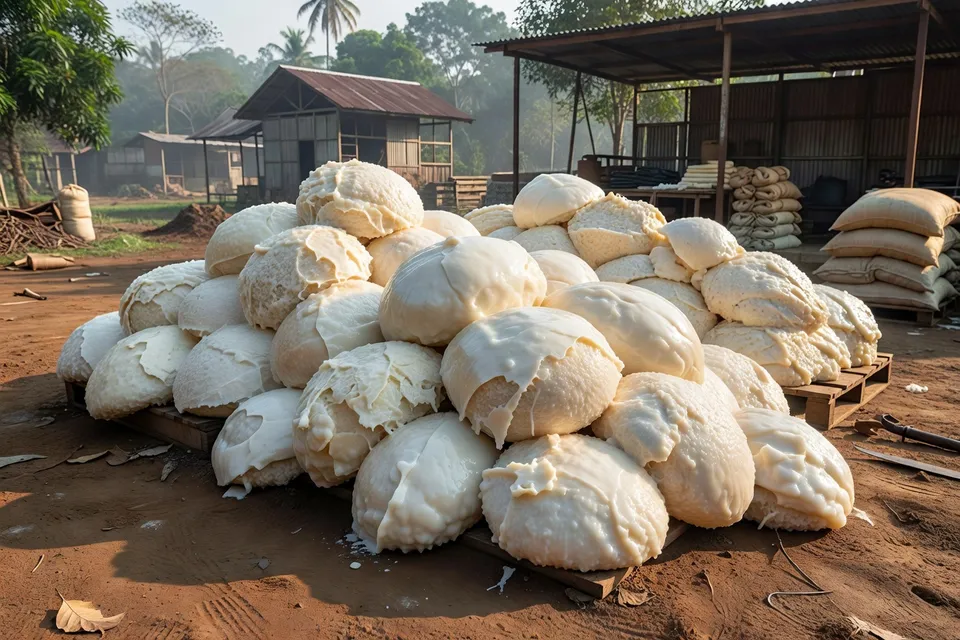
That leaves procurement with a verification task. A processor asking for replacement material needs more than a futures chart: it needs the supplying estate or aggregator, the grade available, the loading location, the earliest sailing and the quantity that can actually be committed. None of those operating details is established in the October market reports.
The Indonesian issue also should not be folded into the Thai rainfall story. Thailand's risk is described mainly through rainfall and flooding in a specific producing region. Indonesia's risk is framed through scarce raw material and weather effects on cup-lump quality and tapping. Those are related supply concerns, not one measured regional outage.
Prices versus physical availability
The price record is strong enough to show that traders are paying attention, but it does not prove that every buyer is short. SunSirs reported that the main Chinese natural-rubber futures contract, RU2701, reached an intraday high of 21,005 yuan per tonne on October 19, a level not seen since February 2017, before retreating but remaining above 20,000 yuan per tonne. The same report attributed the rally largely to production-reduction expectations and weather concerns.
The October 26 market report placed OSE's March 2027 contract at 447.9 yen, down 0.5% for the week, with trading volume falling by 375 lots to 2,978 lots and open interest declining by 105 lots to 4,916 lots. The weekly move was softer, even as the broader uptrend remained intact. That combination argues for caution: the market can retain a bullish supply narrative while short-term positions are reduced.
| Market indicator | October 2026 figure | Period or change |
|---|---|---|
| Natural rubber futures, China RU2701 | 21,005 yuan/tonne | Intraday high, October 19 |
| OSE March 2027 rubber futures | 447.9 yen | Weekly close, October 26; down 0.5% |
| OSE weekly trading volume | 2,978 lots | Week ended October 26; down 375 lots |
| OSE open interest | 4,916 lots | Week ended October 26; down 105 lots |
The table shows price strength in China alongside lighter OSE participation. It does not show a producer allocation, a port closure or a confirmed shortfall in delivered rubber.
Demand can cap the move
The supply concern is not operating alone. SunSirs reported that downstream demand was relatively sluggish and that tire-enterprise procurement remained mainly demand-driven, with limited willingness to build stocks. Trading Economics also noted that lower crude-oil prices made petroleum-based synthetic rubber more competitive, which can divert some demand away from natural rubber.
That substitution channel matters to converters. A higher natural-rubber quote can be passed through only if the finished product buyer accepts it. If tire demand remains weak, processors may delay replenishment rather than chase the prompt market. If synthetic alternatives become cheaper, the physical response to a natural-rubber rally can be smaller than the futures move suggests.
The same report identified a longer-dated weather risk: El Niño conditions were expected to persist through February 2027. That is a forward risk marker, not a production forecast with a quantified loss. It becomes commercially meaningful only if tapping, cup-lump quality, collection volumes or shipment commitments deteriorate in a named producing area.
What buyers can approve
A buyer can reasonably flag October Southeast Asian natural rubber as weather-sensitive, especially for material linked to southern Thailand and Indonesian raw-material collection. A buyer cannot yet approve an emergency regional-shortage assumption from these notices alone.
The minimum checks are practical: confirm the grade and origin, ask whether the material is already produced or still dependent on fresh tapping, obtain a loading date and sailing, and require the seller to state whether any allocation applies. For Thailand, ask whether the supply comes from the rain-affected south or the recovering north. For Indonesia, ask how cup-lump quality is being measured and whether the shortage concerns field supply, collection or delivery.
The next decisive point is the release of fourth-quarter Southeast Asian output after the weather disruption. If tapping resumes and raw material reaches collection channels, the supply premium can unwind, particularly while tire demand stays soft. If southern Thailand remains inaccessible or Indonesian cup-lump quality deteriorates, the market will have a stronger physical basis for the risk already priced into October futures. No producer restart window or allocation review has been given.
Editorial Insights
- What evidence is enough to treat a natural-rubber shipment as physically at risk rather than merely exposed to a higher futures price?
- Ask the seller for the grade, producing origin, production status, loading location, committed quantity and sailing date. A futures rally only establishes that the market is pricing concern; it does not show that your lot is unavailable. Refuse to classify the material as short unless the supplier identifies a collection, quality, logistics or allocation constraint tied to that shipment. The common mistake is to replace a missing shipping commitment with a price chart.
- How should procurement separate southern Thai disruption from broader Thai supply recovery?
- Record the material’s producing area before treating Thai availability as one number. Southern collection may remain constrained by rain, flooding and field access while northern tapping resumes, so a seller’s statement that Thailand is recovering is incomplete without a regional split. Also distinguish rubber already in a warehouse or confirmed shipment from volume dependent on future tapping. The failure mode is approving a substitute or extra coverage on a national headline while the contracted lot comes from the affected south.
- What must be verified when an Indonesian supplier cites raw-material scarcity or cup-lump quality problems?
- Request the affected grade, the supplying estate or aggregator, the measurement method for cup-lump quality, the quantity available and the earliest loading date. “Raw-material shortage” can refer to field supply, collection, quality rejection or delivery, and each creates a different purchasing decision. Do not accept a regional shortage claim as proof of allocation until the seller states whether your account is affected. The practical risk is receiving material that matches the name of the grade but fails the agreed quality window or arrives after the production slot.
- When does a higher natural-rubber price justify changing the formulation or buying synthetic rubber instead?
- Run the substitution decision against delivered cost, qualification status, performance requirements and customer approval—not the futures quote alone. Cheaper petroleum-based synthetic rubber can limit natural-rubber demand, but a formulation change still requires lab checks, processing confirmation and dimensional or physical-property validation. If the alternative is not already approved, it cannot serve as immediate coverage. The usual error is assuming a lower spot price creates usable supply when the conversion, testing and approval sequence consumes the available time.
- What inventory action is justified while Southeast Asian supply remains weather-sensitive but unallocated?
- Protect only the coverage that has a defined production need and a credible replenishment gap. Separate confirmed stock, booked shipments and uncommitted future tapping, then review days of coverage against the grade’s shelf-life and the plant’s qualification limits. Do not approve a blanket regional build merely because futures are elevated; soft tire demand can reduce prompt buying and allow the premium to unwind. Extra inventory also creates its own failure mode when the material outlasts its usable quality window or ties up cash without securing the required origin.
- Which next measurement would turn the current supply-risk premium into a confirmed physical shortage?
- Track recovered tapping days, collection volumes, cup-lump quality results and actual shipment commitments by producing area. The decisive evidence is not another price high but deterioration in a named origin that reduces committed, deliverable rubber. File supplier updates against the grade and lot, and require changes to allocation status or sailing dates to be documented. A common mistake is treating a persistent bullish narrative as confirmation even when field work resumes and downstream demand remains too weak to force additional buying.
References
- 1.Kyrie Dichosa. (2026, October 26). Rubber futures rise. Trading Economics.
- 2.Trading Economics. Rubber. Trading Economics.
- 3.Futures Daily. (2026, October 26). El Niño-driven supply worries push natural rubber prices higher with downside risks. SunSirs.
- 4.Trading Economics. Rubber. Trading Economics.
- 5.TCBS. Rubber prices rise: Which rubber stocks move most in step. TCBS.
- 6.Nur Athirah Mohd Shaharuddin. (2026, October 26). KL rubber market closes mixed amid lower oil prices, supply disruptions. Bernama.
- 7.TDD-Global. Natural rubber weekly report: Bottom support and rebound pressure, Oct. 22. TDD-Global.
- 8.Trading Economics. Rubber. Trading Economics.
- 9.Japan Exchange Group. The weekly rubber futures report. Japan Exchange Group.